Managing Assets: Strategies, Tools and Best Practices for Small Business in 2026
Introduction
Every small business owns assets: cash, inventory, a delivery van, laptops, a brand name and even a customer list. Managing assets means knowing what you own, what it is worth, what it costs to keep, and when to replace it.
Many small business owners skip this work. They buy equipment when they need it, forget about it, and only think about it again when something breaks or tax time arrives. That approach costs money: equipment gets lost, maintenance gets missed, and the books slowly stop matching reality.
The good news is that managing assets does not have to be complicated. A simple list, a regular review and a few good habits are enough for most small businesses. In this guide, you will learn the types of business assets, the strategies that work, the best tools for tracking them, how depreciation works, and the mistakes to avoid.
Table of Contents
What Does Managing Assets Mean for a Small Business?
Managing assets is the practice of tracking everything a business owns across its whole life, from purchase to sale or disposal. It covers physical things, such as equipment and vehicles, and non-physical things, such as software licenses and trademarks.
For a small business, managing assets comes down to four simple questions. First, what do we own? Second, what is each item worth on the books today? Third, what does it cost to keep and maintain? Fourth, when should we repair, replace or sell it?
Good asset management answers all four questions. It starts with a fixed asset register, a simple list of every long-lived item, with its purchase date, cost, location and current value. Without this list, depreciation becomes guesswork and the balance sheet slowly stops being true. Note that managing assets differs from managing investments: the first covers the property the company uses to operate, while the second grows a portfolio of stocks or funds.
Types of Business Assets
Business assets fall into three main groups, and each group is tracked and treated differently in the books.
| Asset Type | What It Includes | Examples |
|---|---|---|
| Current assets | Resources used up or turned into cash within one year | Cash, accounts receivable, inventory, prepaid expenses |
| Fixed assets | Physical property used for more than one year | Buildings, vehicles, machinery, computers, furniture |
| Intangible assets | Valuable items with no physical form | Patents, trademarks, copyrights, goodwill, software licenses, domain names |
Current Assets
Current assets are the resources a business expects to use up or convert to cash within one year. Cash in the bank, money customers owe you for goods already delivered, and inventory ready for sale are all current assets. Managing assets in this group is mostly about cash flow and inventory control.
Fixed Assets
Fixed assets are the physical, long-lived property a business uses to operate rather than to sell: real estate, equipment, delivery vehicles and office furniture. These items stay on the books for years, losing value gradually through wear and use. That gradual loss of value is recorded as depreciation, and fixed assets are where tracking discipline pays off the most.
Intangible Assets
Some of the most valuable things a business owns have no physical form. Intangible assets include patents, copyrights, trademarks, franchises, licenses and goodwill, the value of a good reputation and strong customer relationships. Software licenses and domain names also count for many small businesses. Their cost is spread over their useful life through amortization, a process similar to depreciation.
Why Managing Assets Matters for Small Business
Managing assets well protects your money in several ways. First, it protects cash flow: when you know what you already own, you stop buying duplicates and paying to store or insure things you no longer use. Second, it helps with loans, because lenders look at your assets when they judge whether your business can repay. A clean asset list makes your business look stronger, and our guide to term business lending explains how lenders weigh assets and cash flow.
Third, it saves tax money, since depreciation and equipment deductions only work when records are complete. It also helps when you sell the business, as buyers pay more for clear records. Finally, it prevents surprises: a maintained machine outlasts one ignored until it breaks down on the busiest day of the year.
Asset Management Strategies That Work
You do not need a big system to manage assets well. These strategies work for businesses with ten assets or a thousand.
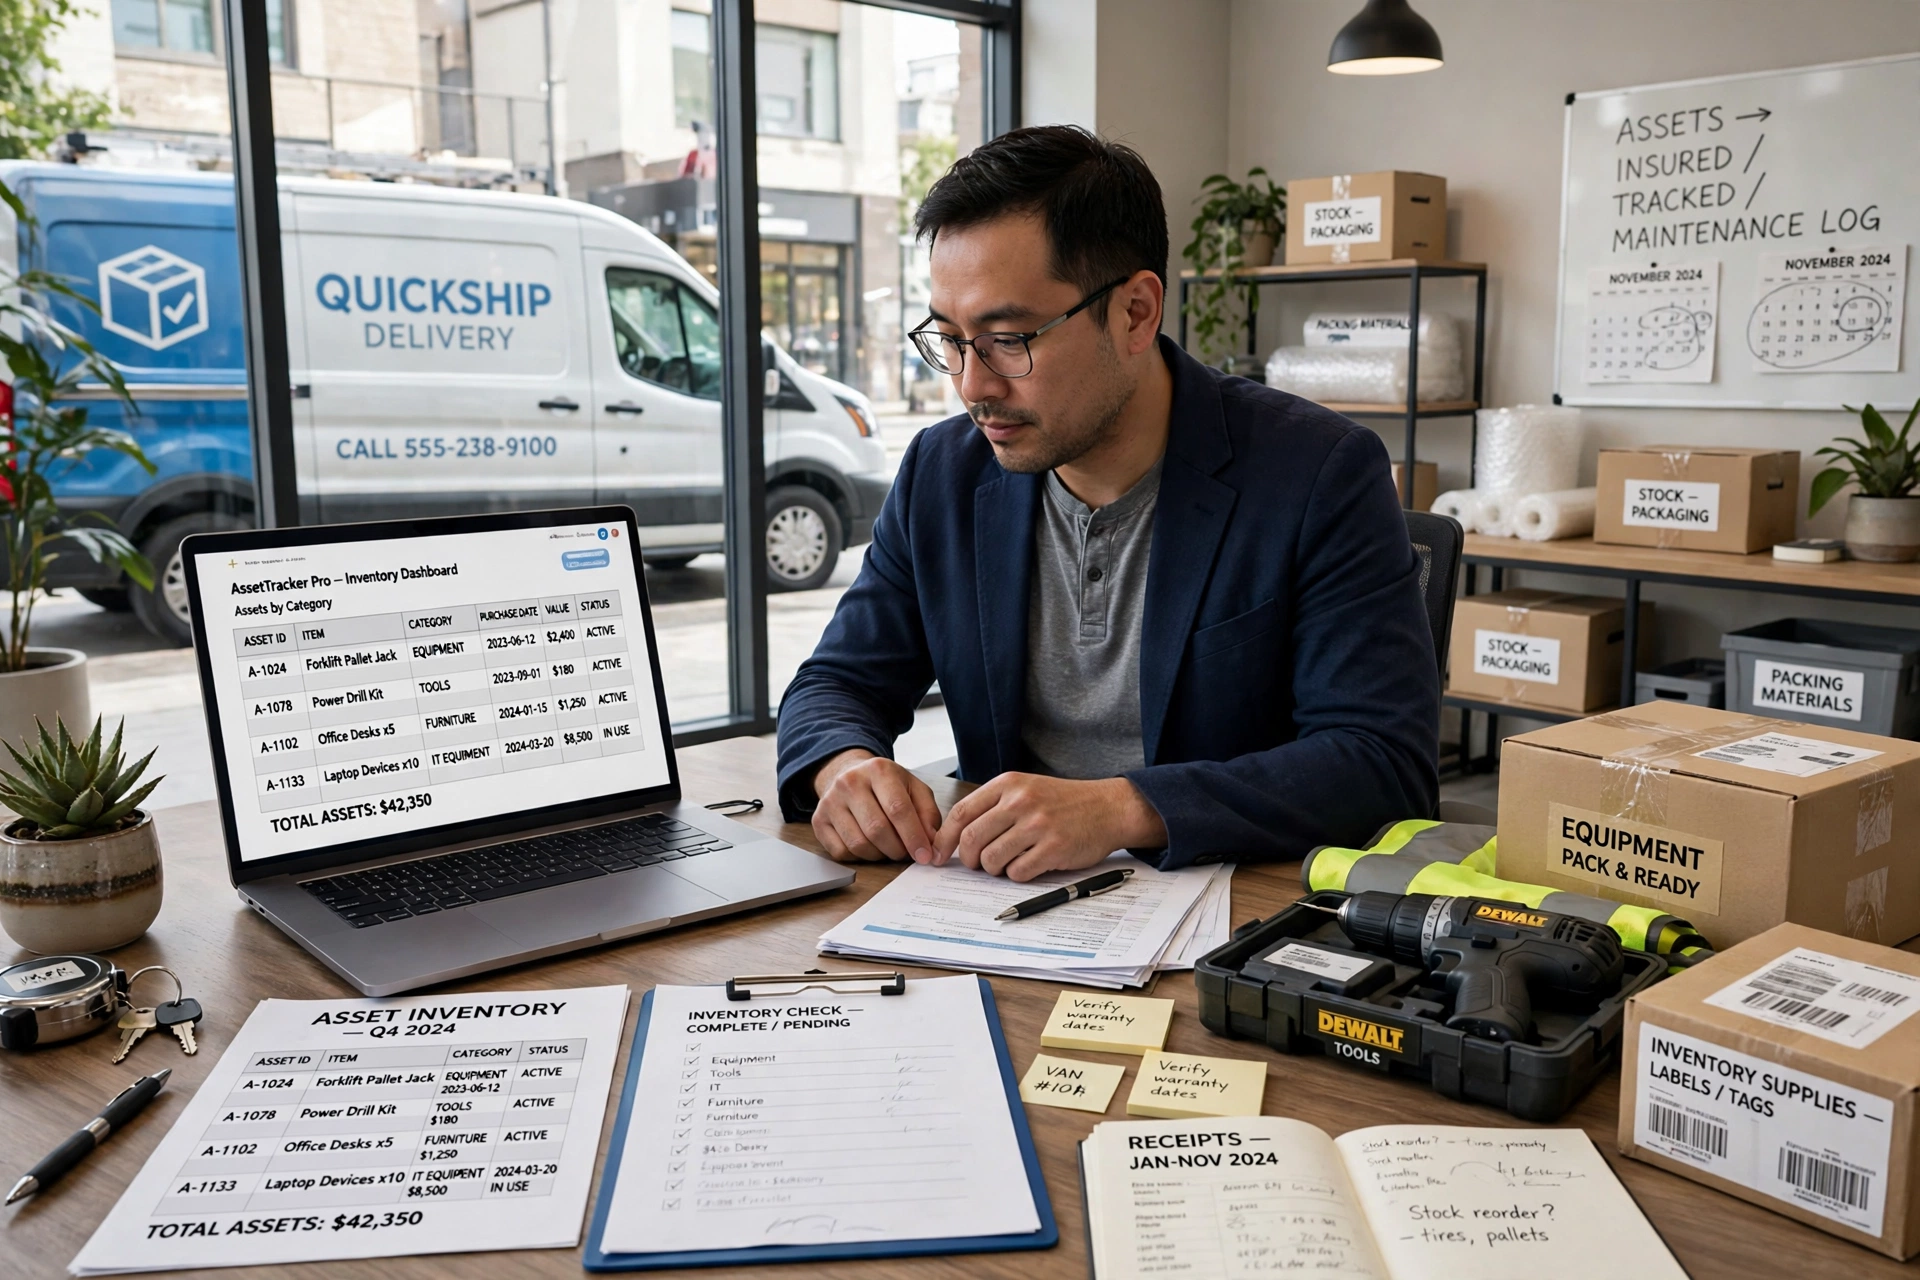
- Build a fixed asset register. List every item that will last more than a year, with its purchase date, cost, serial number, location and who uses it. Update it the day something is bought, moved or sold.
- Set a capitalization threshold. Decide a dollar amount above which a purchase is recorded as an asset instead of a simple expense. Many small businesses use the IRS de minimis safe harbor figure of $2,500 per item.
- Tag everything. Put a barcode or QR code label on each physical asset. A quick scan during a count is faster and more accurate than reading serial numbers by hand.
- Schedule maintenance. Give each important asset a service schedule and stick to it. Regular maintenance is almost always cheaper than emergency repairs.
- Review assets every quarter. Walk through the register and check what is still used, what needs repair and what should be sold. A quarterly review takes an hour and catches problems early.
- Plan replacements before breakdowns. When an asset reaches the end of its useful life, budget for its replacement in advance instead of waiting for it to fail.
- Separate business and personal assets. Never mix personal items into the business register. Mixing them creates tax problems and makes the books unreliable.
- Insure what matters. Make sure valuable equipment and vehicles are covered, and keep the insurance list matched to the asset register.
- Sell idle assets. Equipment sitting unused is cash sitting still. Sell it, and put the money back into the business.
Best Asset Management Tools and Software for Small Business
The right tool depends on what you track: a simple tag-and-scan app fits a small team, while a full register with maintenance and depreciation fits a business with equipment across several sites.
| Tool | Best For | Free Option | Key Features |
|---|---|---|---|
| Sortly | Small teams replacing spreadsheets | Free plan for up to 100 items | Barcode and QR scanning, photos, check-in and check-out, low-stock alerts |
| Asset Panda | Businesses that want one configurable platform | Free trial only | Barcode and QR scanning, maintenance tracking, depreciation |
| EZOfficeInventory | Mid-size teams with mixed assets | Free trial only | GPS and RFID tracking, maintenance scheduling, check-in and check-out |
| Snipe-IT | IT teams tracking laptops and devices | Free and open source | Check-in and check-out, license tracking, audits |
| AssetTiger | Small organizations that want simple tag-and-scan tracking | Free trial only | Barcode labels, warranty tracking, depreciation reports |
According to a 2026 comparison by PlugRoute, which cites Capterra’s 2025 Asset Management Software Adoption Report, 66 percent of small businesses still track assets in spreadsheets. A spreadsheet works for a handful of items, but it breaks down as the list grows.
Sortly is the easiest starting point for most small businesses. Its free plan covers up to 100 items, and its paid plan starts at $24 per month for up to 2,000 items, according to PlugRoute’s 2026 roundup. It also connects with QuickBooks Online, which keeps the books and the asset list in step. Prices change, so check the vendor’s site first. For IT equipment, Snipe-IT is a strong free and open-source option, while EZOfficeInventory and Limble CMMS add maintenance scheduling for equipment that needs regular servicing. Whatever tool you choose, the asset register and the accounting books should agree. Our guide to the best small business accounting software compares the leading options for keeping those books accurate.
Asset Tracking and Depreciation
Tracking is only half the job. The other half is recording how each asset loses value over time, a process called depreciation.
How Depreciation Works
Depreciation spreads the cost of a tangible asset across the years it will be used, so the expense appears in the periods that benefit from it rather than all at once. The most common methods are straight-line, declining-balance and units-of-production.
The straight-line method is the simplest and the most common in small business books. The formula is:
(Cost – Salvage value) / Useful life = Annual depreciation
For example, a machine that costs $23,800, with a salvage value of $2,800 and a seven-year useful life, depreciates at $3,000 a year. That example comes from a worked calculation published by GlassJar in its small business asset management guide. Declining-balance takes larger deductions in the early years, while units-of-production ties depreciation to actual use.
Book Depreciation vs Tax Depreciation
Book depreciation and tax depreciation are two different calculations. For taxes, the IRS uses the Modified Accelerated Cost Recovery System, known as MACRS, and the rules are set out in IRS Publication 946, How to Depreciate Property.
Section 179 of the tax code lets a business deduct the full purchase price of qualifying equipment in the year it is bought. For the 2026 tax year, the maximum Section 179 deduction is $2,560,000, with the limit phasing out once total equipment purchases pass $4,090,000, according to the tax code as summarized by LegalClarity. These limits change, so confirm the current figures with your accountant.
What Your Asset Register Should Record
A good register records the purchase date and cost, the supplier, the serial number, the location, the person responsible, the useful life, the depreciation method, the salvage value and the accumulated depreciation. Accumulated depreciation is a contra-asset account that sits under the asset on the balance sheet and reduces its book value. For intangible assets, the matching process is amortization, which spreads the cost of items such as patents and software licenses over their useful lives.
Managing Assets for Cash Flow and Liquidity
Assets and cash flow are closely linked. Cash is itself an asset, and every other asset either helps you earn cash or ties cash up. Working capital, which is current assets minus current liabilities, is the simplest measure to watch. When it is healthy, the business can pay its bills on time and handle a slow month. When it is thin, even a profitable business can run into trouble.
Three habits protect liquidity. First, keep inventory lean, since stock on a shelf is cash that cannot be used elsewhere. Second, collect receivables on time, since money owed is only an asset when it arrives. Third, think twice before tying up cash in equipment; leasing is often smarter for technology that becomes outdated quickly.
If cash is tight, look at the asset register before looking at a loan. Selling an idle machine or unused vehicle can free up thousands of dollars without adding debt, and a strong asset list helps any loan application. Our guide on what a business credit score is and how to build it explains how lenders judge the financial health of a small business.
A Practical Example: Managing Assets in a Small Delivery Business
Maria runs a small delivery business with two vans, four laptops, a printer and a small warehouse. Last year she started managing assets properly, and the change paid for itself in a few months.
First, she built an asset register. The two vans were the biggest items. Van 1 cost $28,000 new, with an expected salvage value of $3,000 after five years. Using the straight-line method, its depreciation is ($28,000 – $3,000) / 5 years, which is $5,000 a year, or about $417 a month. Van 2 was older and fully depreciated, so it was time to plan a replacement instead of another big repair.
Next, she tagged everything. Each laptop and tool got a QR code label, and the register recorded who held each item. The first count found a forgotten spare printer and a laptop a former employee had never returned. The laptop was recovered, and the printer sold for $350.
Then she reviewed the register each quarter. In one review she found that Van 2 needed a $1,200 repair, while a dealer offered $6,000 for it as a trade-in. She took the trade-in and put the $6,000 toward a newer van. The result was simple: Maria knew what she owned, what it was worth, and what it cost to keep, and she stopped spending money on equipment that was no longer earning its keep.
Common Mistakes When Managing Assets
Most asset problems come from a short list of avoidable mistakes.
- No asset register at all. If there is no list, nobody knows what the business owns. Start with a spreadsheet, then move to a tool when the list grows.
- Mixing personal and business assets. Personal items in the business books create tax trouble and confuse the true value of the business.
- Forgetting depreciation. Skipping depreciation makes profits look higher than they are and leaves tax deductions unclaimed.
- Buying before checking what you own. Many businesses buy a second copy of something they already own. Check the register first.
- Ignoring maintenance. A missed service turns a small job into a big repair bill, and often at the worst possible time.
- No insurance records. If equipment is stolen or damaged, an outdated insurance list can mean a smaller claim or no claim at all.
- Keeping dead assets. Broken or unused equipment takes up space and still shows on the books. Sell it or dispose of it properly and record the disposal.
- No disposal records. When an asset is sold or scrapped, the register and the books must be updated on the same day, or the balance sheet will keep showing value that no longer exists.
- Choosing the business structure as an afterthought. How you hold assets depends on your business structure. Our guide to LLC services explains how an LLC affects what the business owns and how it is protected.
Frequently Asked Questions
1. What is asset management in a small business?
It means knowing what the business owns, what each item is worth, what it costs to keep, and when to repair, replace or sell it. It covers everything from cash and inventory to vehicles, equipment and trademarks, and it is tracked in a fixed asset register.
2. What are the three main types of business assets?
Current assets, fixed assets and intangible assets. Current assets, such as cash, receivables and inventory, are used up or turned into cash within a year. Fixed assets, such as buildings, vehicles and machinery, are physical property used for more than one year. Intangible assets, such as patents and software licenses, have value but no physical form.
3. How do I start tracking my business assets?
List every item that will last more than a year, with its purchase date, cost, serial number and location. Put a barcode or QR code label on each physical item, choose one person to keep the list updated, and review it every quarter. A spreadsheet is fine at the start, and a tool such as Sortly or Snipe-IT makes sense once the list grows.
4. What is the best asset management software for a small business?
It depends on what you track. Sortly is the easiest starting point for small teams, with a free plan for up to 100 items. Snipe-IT is a strong free open-source choice for IT equipment. Asset Panda and EZOfficeInventory suit businesses that also need maintenance scheduling and depreciation reports.
5. How does depreciation work for small business assets?
Depreciation spreads the cost of a tangible asset over its useful life. The straight-line method divides the cost minus the salvage value by the number of years the asset will be used. Tax depreciation follows IRS rules under MACRS, and Section 179 may allow qualifying equipment to be deducted in the year of purchase.
6. What is the difference between current assets and fixed assets?
Current assets are used up or converted to cash within one year, such as cash, inventory and money owed by customers. Fixed assets are long-lived physical property, such as vehicles, machinery and buildings, used for more than one year. Fixed assets are depreciated over time, while current assets are not.
7. Should I buy or lease business equipment?
Buying usually costs less over the long run and lets you claim depreciation, while leasing keeps cash free and makes sense for technology that becomes outdated quickly. Compare the total cost of each option, including maintenance, insurance and resale value.
8. How often should I review my business assets?
Review the asset register at least once a quarter. Check what is still used, what needs maintenance, what has lost value and what should be sold. A full physical count once a year also catches unrecorded moves, losses and disposals.
Final Thoughts
Managing assets is not about buying expensive software or hiring a specialist. It is about knowing what you own, keeping a simple list, and reviewing it regularly. A small business that tracks its assets makes better decisions about buying, repairing, selling and borrowing.
Start today with a register, even if it is only a spreadsheet. Tag your biggest items, record their purchase dates and costs, and set a date for your first quarterly review. Over time, move to a proper tracking tool and let your accountant check the depreciation figures.
Disclaimer: This article is general information for small business owners and is not tax, legal or financial advice. Tax rules and deduction limits change, so talk to a qualified accountant or tax professional before making decisions about depreciation, Section 179 or the treatment of any asset.
3 Comments