Net Operating Income Formula Calculation and Examples
If you own a rental property or run a business, you need one number that tells you whether the operation itself makes money. That number is net operating income. It shows how much profit your property or business produces from its normal work, before loan payments and taxes get in the way.
Many new investors confuse this number with total profit. They are not the same thing. Net operating income leaves out mortgage payments, income taxes, and one-time gains or losses, so it gives you a clean view of day-to-day performance.
In this guide, you will learn the simple formula, how to calculate net operating income step by step, and how to use it to compare properties and improve your returns.
Table of Contents
What Is Net Operating Income?
Net operating income, often called NOI, is the income left over after you subtract operating expenses from the revenue a property or business earns from its normal operations. It is one of the most used numbers in commercial real estate, and it also works for any small business that wants a clear picture of operating profit.
Think of it this way. A rental building brings in rent every month and pays regular bills such as property taxes, insurance, repairs, and management fees. What remains after those bills is the operating profit of the building.
Investors like this number because it is simple to compare. Two buildings in the same city can have very different mortgages and different owners, but their operating results can still be compared side by side. A clear definition helps here, and Investopedia explains the concept in plain terms at https://www.investopedia.com/terms/n/netoperatingincome.asp.
Net Operating Income Formula
The formula is short and easy to remember:
Net Operating Income = Gross Operating Income − Operating Expenses
Gross operating income is all the revenue the property or business earns from normal operations. For a rental property, that means rent plus other regular income such as parking fees, laundry income, and pet fees, minus the money lost to empty units.
Operating expenses are the regular costs of running the property: property taxes, insurance, maintenance, repairs, utilities, and management fees. They do not include mortgage payments, income taxes, or major improvements.
The Corporate Finance Institute gives a detailed breakdown of the formula and its parts at https://corporatefinanceinstitute.com/resources/valuation/net-operating-income-noi/.
How to Calculate Net Operating Income
You can calculate net operating income for any rental property in five steps. Follow them in order, and keep your numbers based on a full year so seasonal changes do not distort the result.
Step 1: Add up all potential rental income. Multiply the monthly rent of each unit by 12 months and add the units together. This is your gross potential income.
Step 2: Add other income. Include parking fees, laundry income, pet fees, and any other regular income the property earns. Add this to the gross potential income.
Step 3: Subtract vacancy and credit losses. No building is full all year. A common allowance is 5 percent of gross potential income. Subtracting this gives you the effective gross income.
Step 4: Add up all operating expenses. List every regular cost: property taxes, insurance, maintenance, repairs, management fees, utilities, and marketing. Do not include the mortgage payment, income taxes, or capital improvements.
Step 5: Subtract operating expenses from effective gross income. The result is the NOI for the year.
Worked Example
Here is a full net operating income example using a small 10-unit apartment building. Each unit rents for $1,200 per month.
Potential rental income: 10 units × $1,200 × 12 months = $144,000
Other income: laundry $3,600 + parking $6,000 = $9,600
Gross potential income: $144,000 + $9,600 = $153,600
Vacancy allowance (5 percent): $153,600 × 0.05 = $7,680
Effective gross income: $153,600 − $7,680 = $145,920
Operating expenses for the year:
Property taxes: $12,000
Insurance: $6,000
Maintenance and repairs: $9,000
Property management: $11,674
Utilities: $8,400
Marketing: $2,000
Total operating expenses: $49,074
NOI: $145,920 − $49,074 = $96,846
This building produces $96,846 per year before mortgage payments and taxes. Using the best small business accounting software can automate much of this tracking, so the numbers stay accurate month after month: https://tubeweekly.com/best-small-business-accounting-software/
Net Operating Income vs Net Income
People often mix up NOI and net income. The biggest difference is that NOI stops at operations, while net income goes all the way to the bottom line after financing and taxes.
| Net Operating Income | Net Income | |
|---|---|---|
| What it measures | Profit from normal operations | Total profit after all costs |
| Mortgage payments | Not included | Included |
| Income taxes | Not included | Included |
| Depreciation | Not included | Included |
| One-time gains or losses | Not included | Included |
| Best use | Comparing properties | Measuring total business profit |
Use NOI when you want to compare two properties or judge how well a building is run. Use net income when you want to know what the owner actually keeps after paying the bank and the tax authority. Both numbers matter, but they answer different questions.
What Counts as Operating Income and Expenses
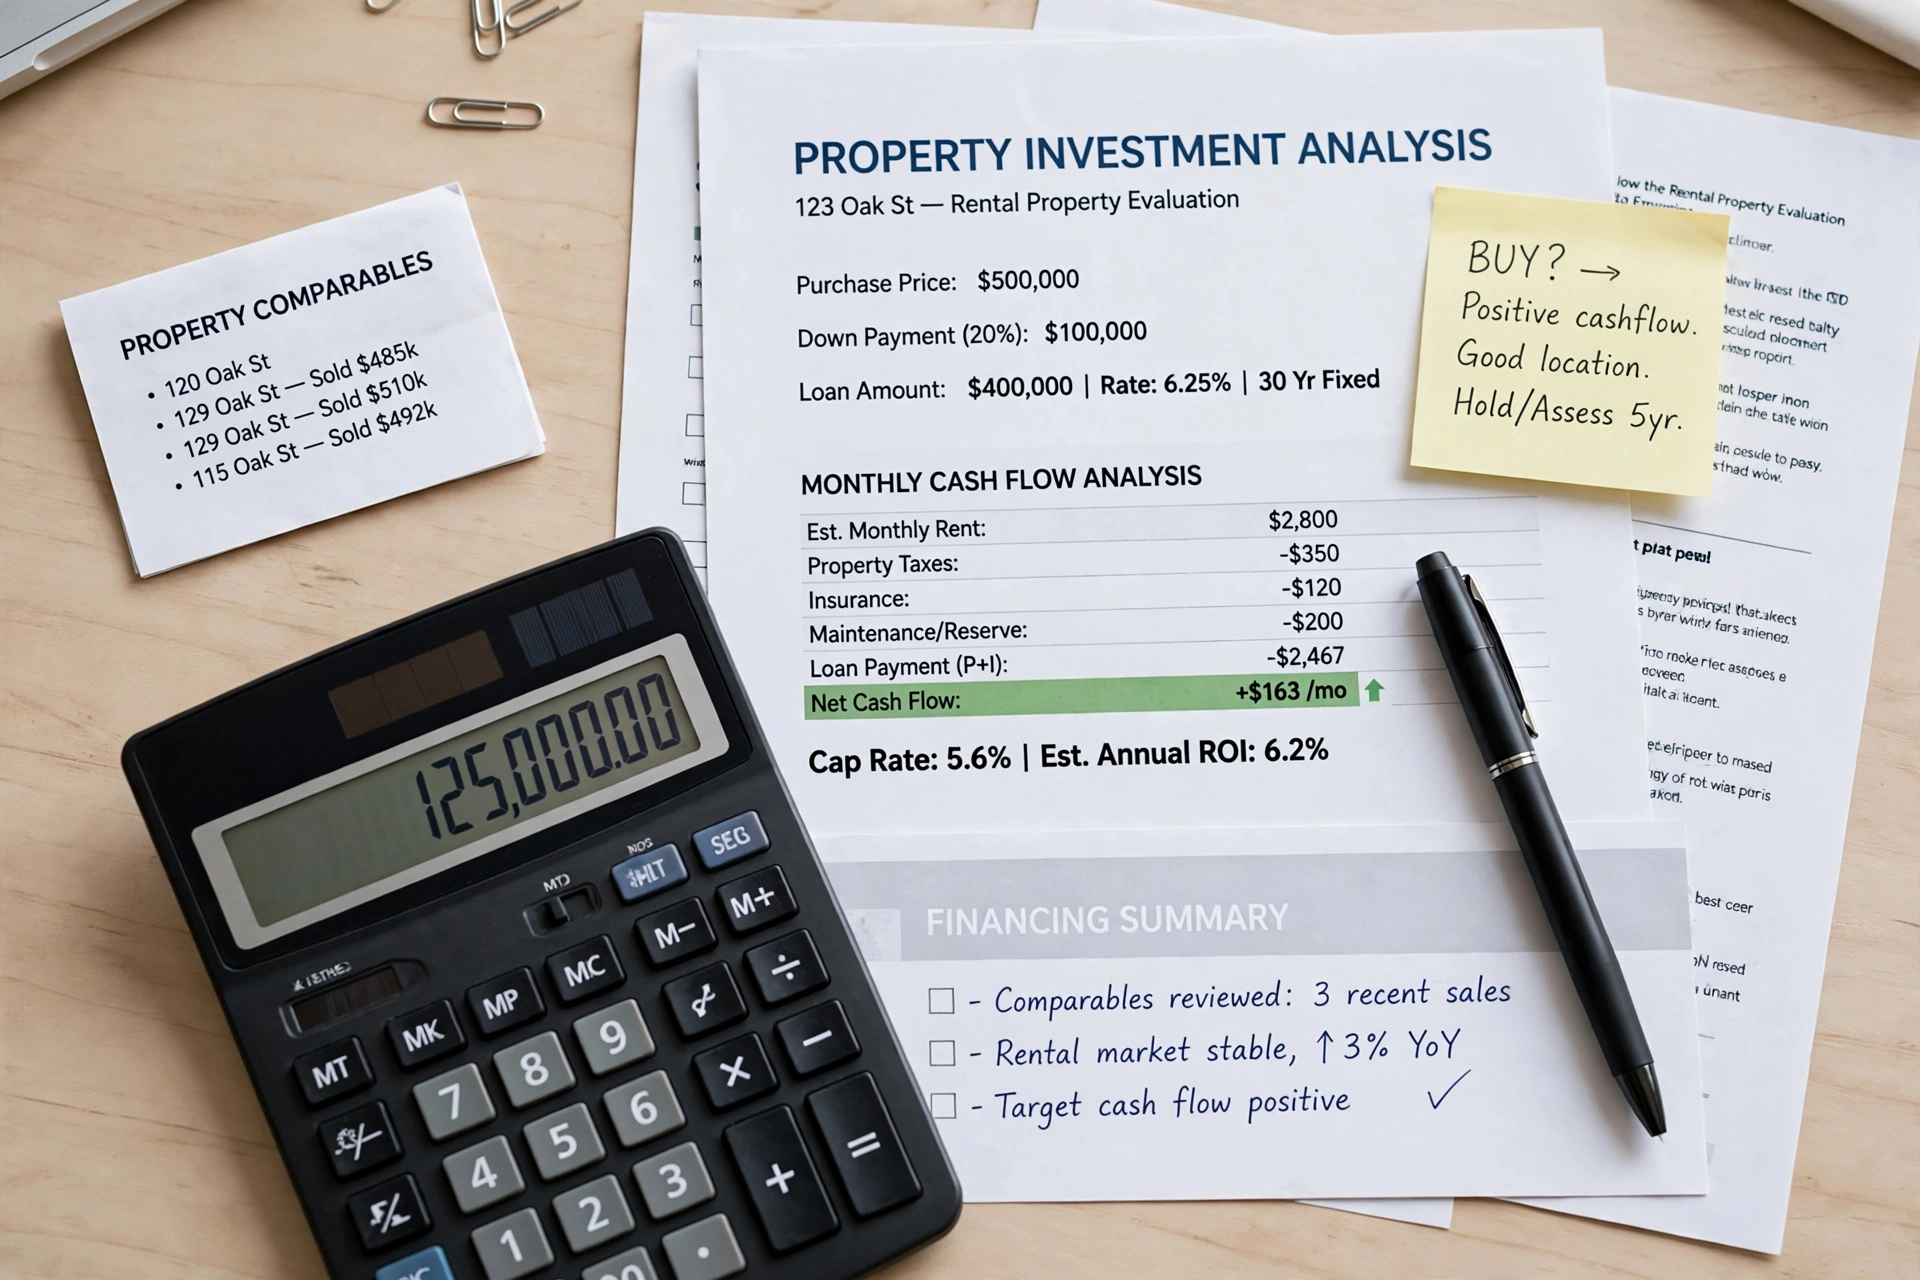
To get net operating income right, you must sort every dollar into the correct group. A single misplaced item can change the result and mislead a buyer or a lender.
Operating income includes rent from tenants, parking fees, laundry income, pet fees, vending income, and fees for storage units. It does not include money from selling the property, insurance payouts, or tax refunds. Those are one-time items, not operating income.
Operating expenses include property taxes, insurance, routine maintenance, repairs, property management fees, utilities paid by the owner, landscaping, pest control, and marketing to find tenants. They do not include mortgage payments, income taxes, depreciation, or capital improvements such as a new roof or a full renovation. A monthly bank reconciliation keeps your income and expense records accurate, so your NOI is based on real numbers instead of guesses: https://tubeweekly.com/bank-reconciliation/
Capital improvements deserve special care. A new roof or heating system is a large one-time cost that adds value to the property, so it stays out of the NOI calculation. Repairs, on the other hand, fix something broken and keep the building running, so they count as operating expenses.
Why Net Operating Income Matters for Real Estate and Business
Lenders and buyers trust net operating income because it shows the true earning power of a property. A buyer can look at the NOI of two buildings and see which one runs better, even if the two owners have very different loans.
The most common use is the cap rate. To find it, divide the net operating income by the property price. In our example, a building earning $96,846 that costs $1,200,000 has a cap rate of 8.07 percent. A higher cap rate usually means a higher return, though it can also mean higher risk, so always check the location and condition too.
Banks also use NOI when they decide how much to lend. A strong NOI tells the bank that the property can cover its loan payments, which makes approval more likely. For a small business, the same logic applies: a healthy operating profit shows that the core business works, and funding or a partner becomes easier to find. Good habits like managing assets carefully help you protect the value behind the income, and you can read more about that at https://tubeweekly.com/managing-assets/
The IRS treats rental income and expenses under its own rules, and its guidance on rental income and expenses is useful background at https://www.irs.gov/taxtopics/tc414.
How to Improve Net Operating Income
Improving NOI comes down to two levers: raise income or lower expenses. The best plans work on both sides at the same time.
Start with income. Review your rents once a year against similar units nearby. If your rents are well below the market, a small increase can add thousands of dollars per year. Fill empty units fast, because every empty month is lost income. You can also add small income streams such as paid parking, storage space, or laundry.
Then look at expenses. Get new insurance quotes every year, since rates change. Fix small maintenance problems early, before they turn into large repairs. If you pay for utilities, consider energy-saving lights or better insulation. Review your property management fee and ask what it covers.
Do not cut costs that hurt the property. Skipping maintenance may raise NOI this year, but it pushes tenants away and creates bigger bills later. The goal is a building that earns more and stays in good shape.
Common Mistakes to Avoid With Net Operating Income
The most common mistake is including the mortgage payment as an operating expense. The mortgage is a financing cost, not a cost of running the building. Including it makes the NOI look lower than it really is, and it makes fair comparisons impossible.
Another mistake is forgetting the vacancy allowance. Even a good building has empty units between tenants. With no allowance, you will overstate the income and may overpay for the property.
A third mistake is counting capital improvements as operating expenses. A new roof is not a monthly bill, and treating it as one distorts the NOI. Keep one-time improvements separate from regular costs.
Finally, do not use gross rent instead of effective gross income. Gross rent assumes every unit is full all year, while effective gross income subtracts vacancy and credit losses first. That is the number the formula needs.
Net Operating Income Practical Example
Here is a second example, this time for a small duplex. Two units rent for $1,500 per month each, so the annual rent is $36,000. Other income from a parking space adds $1,200 per year, bringing gross potential income to $37,200.
A vacancy allowance of 5 percent equals $1,860, so effective gross income is $35,340.
Annual operating expenses are property taxes $4,800, insurance $2,400, maintenance $3,000, property management $2,827, utilities $2,400, and miscellaneous costs $600. The total is $16,027.
Subtract the expenses from the effective gross income, and the net operating income is $19,313 per year.
This duplex earns $19,313 before mortgage payments and taxes. If the mortgage costs $14,400 per year, about $4,913 is left before taxes. NOI tells you what the property earns, and the mortgage tells you what the financing costs. Together they show whether the deal works.
Frequently Asked Questions
What is a good net operating income?
There is no single good number, because it depends on the size and price of the property. A better test is the cap rate, which is NOI divided by the property price. Many investors look for a cap rate between 5 and 10 percent, though the right range depends on the city, the property type, and the risk.
Is net operating income the same as profit?
No. NOI is the profit from normal operations only. True profit, or net income, also subtracts mortgage payments, income taxes, depreciation, and one-time items. NOI is usually higher than net income for the same property.
Does NOI include mortgage payments?
No. Mortgage payments are financing costs, not operating costs. Two owners can have very different mortgages on the same building, and the NOI stays the same for both. That is exactly why investors use it to compare properties.
How do you calculate NOI for a rental property?
Add up all rental income and other regular income, subtract a vacancy allowance to get effective gross income, then subtract all operating expenses. The formula is NOI = Gross Operating Income − Operating Expenses.
Can NOI be negative?
Yes. If operating expenses are higher than effective gross income, NOI is negative. That usually means rents are too low, vacancy is too high, or expenses are out of control. A negative NOI is a warning sign that the property needs attention fast.
Final Thoughts
NOI is one of the simplest and most useful numbers in real estate and small business. It shows what a property or business earns from its normal work, without the noise of loans, taxes, and one-time events.
Learn the formula, run the numbers on any property you consider, and compare results with the cap rate. When you know your NOI, you can spot a good deal, avoid a bad one, and plan to raise income or cut waste. That is how small investors build steady returns over time.